Forecasting · 2025–2026
Forecasting the Effective Federal Funds Rate
Can a model forecast the federal funds rate better than repeating last month's rate?
I compared Ridge and Random Forest with a baseline that repeats last month's rate. My first pipeline let information from the holdout period leak into training, so I rebuilt it, locked the design, and only then tested it on 114 later months.
Result: Ridge cut RMSE, a standard forecast-error measure, by 16% (0.1606 vs. 0.1922). Its gain on a second error measure, MAE, was much smaller.
Forecast error on 114 later months
RMSE in percentage points · lower is better
Ridge
0.1606
Last month's rate
0.1922
Random Forest
0.2368
From the project repository. Bars start at zero.
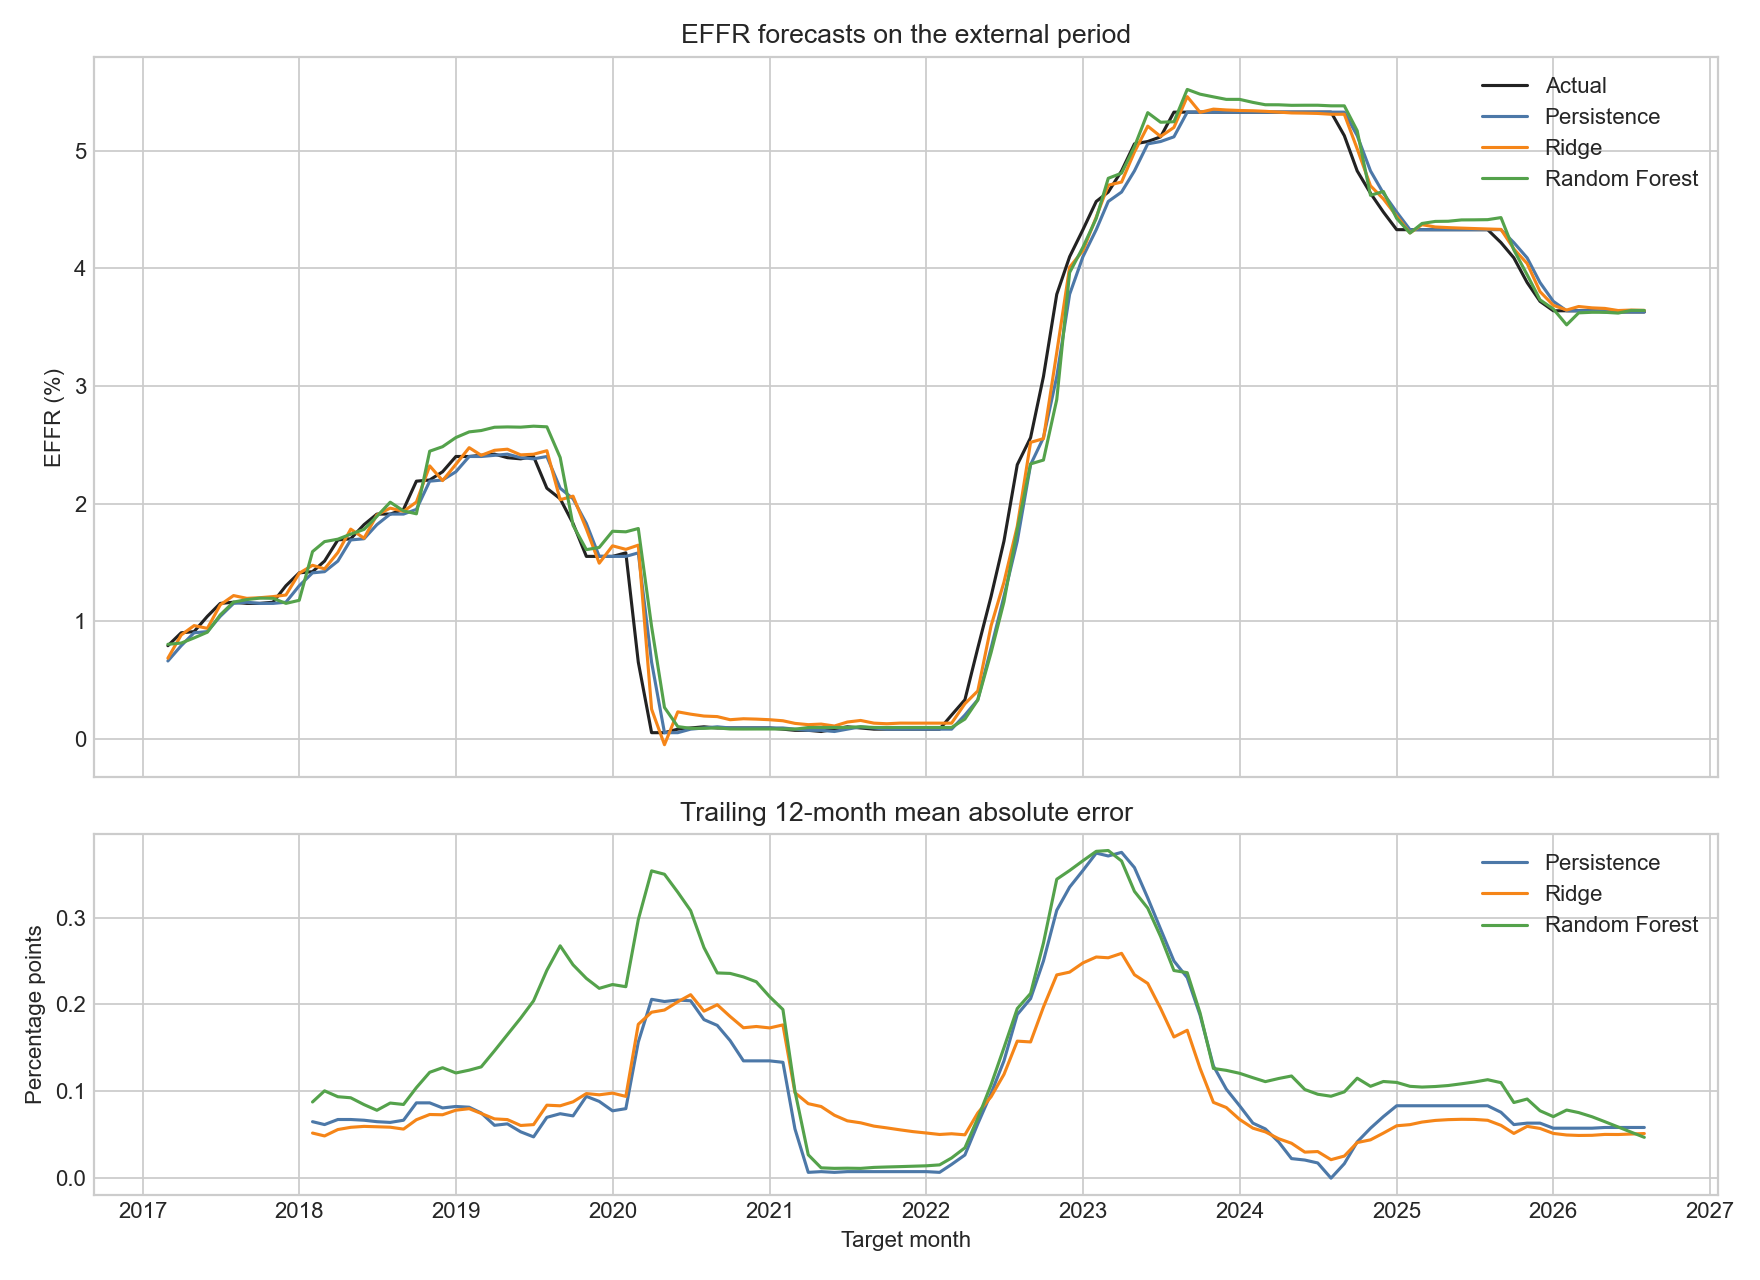
Forecast comparison · open the full-size plot ↗
 PostgreSQL
 MySQL
 Python
 Flask
 Git
 pytest
 scikit-learn
 PyTorch


